For the modern retail investor, the capital market can feel like an existential labyrinth. The rise of zero-fee trading platforms, algorithmic high-frequency trading, and 24-hour financial news cycles have turned investing into a hyper-stimulating landscape. Decisions are frequently driven by emotional hype, temporary market trends, or panic. However, in the upper echelons of asset management, investing is treated as a cold, calculated discipline of risk management. True investment success is not built on predicting the future; it is built on managing uncertainty through a structured, scientifically verified framework.
To transition from a speculative market participant to a sophisticated capital allocator, you must move past the noise of short-term stock tips. A professional investment strategy demands a deep understanding of academic financial theories—such as modern portfolio theory and factor-based investing—balanced against the operational mechanics of real-world markets. This comprehensive guide deconstructs the foundational math of institutional asset allocation, evaluates the primary pillars of modern strategy, and outlines a tactical blueprint to engineer your own resilient investment engine.
Part 1: The Foundations of Asset Pricing and Risk Premium

If an asset class carries zero risk, its return will naturally gravitate toward the baseline rate of inflation, resulting in zero real wealth growth over time. Conversely, if an asset promises double-digit returns, it structurally embeds significant volatility or liquidity risks. The core objective of an institutional investment strategy is not to eliminate risk entirely, but to systematically isolate and hold risks that are highly compensated over long-term historical horizons.
This isolation process relies heavily on Modern Portfolio Theory (MPT), pioneered by economist Harry Markowitz. MPT mathematically proves that an asset’s risk should not be evaluated in isolation, but by how it behaves in tandem with the rest of a portfolio. By combining asset classes that possess a low or negative Correlation Coefficient—meaning they move independently of one another during economic shifts—an investor can significantly reduce the portfolio’s aggregate volatility without sacrificing its long-term expected returns.
Part 2: The Core Framework Strategies Compared
The global financial system offers dozens of tactical frameworks to capture these risk premiums. For a sophisticated individual investor, the three most reliable and scalable investment strategies include:
The Tactical Investment Matrix
| Strategy Framework | Operational Core Philosophy | Structural Asset Classes | Primary Risk Mitigation |
| Passive Indexation (The Bogleheads Model) | Captures total market beta by purchasing low-cost, capitalization-weighted index funds that track entire stock and bond markets. | Global broad-market equities, total bond market instruments. | Eliminates idiosyncratic risk (the risk of individual companies failing) through radical diversification. |
| Factor-Based Investing (The Smart Beta Model) | Tilts a core portfolio toward specific, statistically verified characteristics that historically outperform the broader market over time. | Value equities, small-cap companies, high-momentum stocks, quality balance sheets. | Exploits persistent behavioral errors of investors and structural economic anomalies. |
| Core-and-Satellite Model (The Hybrid Approach) | Anchors 80% of the portfolio in highly stable passive index funds, while allocating 20% to active, tactical investments. | Index funds (Core) combined with direct real estate, private equity, or select sector plays (Satellite). | Restricts high-risk active speculation to a small, isolated ring-fenced sector of the total balance sheet. |
Part 3: The Mechanics of Portfolio Construction
Building an institutional-grade investment strategy requires executing a strict, step-by-step structural protocol that removes human emotion from the asset deployment phase.

Step 1: The Strategic Asset Allocation (SAA)
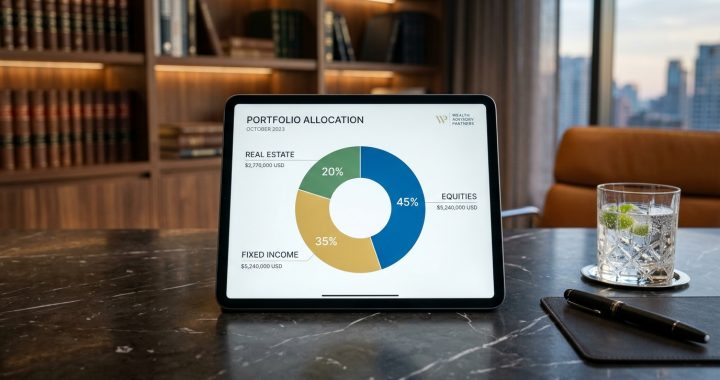
Your SAA is the single most important determinant of your long-term performance, accounting for over 90% of the variance in a portfolio’s returns. You must define your targeted equity-to-bond ratio (e.g., 80% stocks, 20% bonds) based strictly on your Risk Capacity (how much loss your financial timeline can physically sustain) and your Risk Tolerance (how much volatility your psychology can handle without panicking).
Step 2: Cost Minimization and Efficiency Optimization
In the arithmetic of investing, management costs are a direct drag on compound interest. A professional strategy ruthlessly prioritizes Expense Ratios. Opt for institutional-grade exchange-traded funds (ETFs) or mutual funds with expense ratios below 0.15% annually. Every dollar saved in administrative fees remains inside your portfolio, compounding quietly over decades.
Step 3: Dollar-Cost Averaging (DCA) and Systematic Inflows
Attempting to time the market—waiting for a crash to buy or selling before a perceived correction—is statistically a losing game for retail investors. Implement a strict DCA protocol. Automate your accounts so that a fixed dollar amount is deployed into your target asset allocation on a recurring schedule (e.g., every month), completely independent of prevailing market headlines or macroeconomic predictions. DCA guarantees that you automatically purchase more shares when prices are low and fewer shares when prices are high.
Part 4: The Psychology of Volatility
The finest mathematical investment strategy will catastrophically fail if the investor lacks the behavioral discipline to execute it during a crisis. Market corrections are not structural anomalies; they are normal, recurring features of the capitalist system.
When a major macroeconomic shock occurs and the values of your global stock indexes plummet by 20% or 30%, the human brain activates its primitive fight-or-flight response. This emotional panic often drives investors to liquidate their portfolios at the absolute bottom of a crash, locking in permanent capital losses.
The Professional Reframe: Realize that market volatility is the exact price of admission for long-term compounding growth. The high returns delivered by equities over decades exist because they are volatile. If there were no drops, there would be no risk premium. View a bear market not as a systemic disaster, but as a temporary structural sale on global corporate equity.
Conclusion: The Automated Utility
Ultimately, a world-class investment strategy transforms your wealth from a chaotic gambling system into a quiet, highly predictable financial utility company. By grounding your framework in academic portfolio design, minimizing operational costs, automating your capital inflows, and maintaining absolute emotional discipline during market corrections, you establish complete control over your economic perimeter. Your portfolio stops being a source of daily anxiety and becomes what it was always engineered to be: a sophisticated, relentless machine that converts your retained capital into permanent financial security.