In the vocabulary of modern economics, few phrases are as frequently used—and as deeply misunderstood—as “financial independence.” To the casual consumer, it evokes images of early retirement, endless leisure, or sudden lottery wealth. However, viewed through the lens of structural asset management and behavioral finance, financial independence is not a vague lifestyle aesthetic; it is a precise mathematical reality. It is the exact point at which an individual’s accumulated compounding assets generate enough yield to cover their structural living expenses, rendering mandatory corporate employment entirely optional.
To transition from a wage-dependent economic unit to a self-sustaining financial fortress, one must move past superficial saving tips. Achieving true independence requires a deep understanding of investment mathematics, the mechanics of safe withdrawal rates, and a calculated engineering of your personal economy. This comprehensive guide breaks down the core structural equations of the Financial Independence, Retire Early (FIRE) framework, analyzes the real-world metrics of capital preservation, and provides a tactical blueprint to construct your own runway to freedom.
Part 1: The Core Equation — The Cross-Over Point
The foundation of financial independence relies on a singular, clean architectural milestone known in wealth management as the Cross-Over Point.

For the vast majority of society, survival is tied to a linear exchange: selling time and active labor for an ongoing wage. If the labor stops, the cash inflow evaporates, risking immediate household instability. The Cross-Over Point permanently breaks this dependency. It occurs when your passive asset yield—derived from stock dividends, bond coupons, real estate distributions, or equity growth—completely matches or exceeds your total household overhead. At this precise junction, you are structurally independent. Work becomes a matter of purpose and choice, rather than an existential obligation.
To accurately locate your personal Cross-Over Point, you must first establish your True Baseline Overhead. This requires tracking every dollar of localized spending over a trailing 12-month period to account for seasonal adjustments, insurance lines, and unexpected capital depreciation. Once you identify your true annual consumption number, you can deploy the foundational math required to build your freedom fund.
Part 2: The Rule of 25 and the Safe Withdrawal Rate
How much capital does a household actually need to accumulate to safely step away from a mandatory paycheck forever? The answer was discovered by researchers at Trinity University in a landmark financial study commonly referred to as the Trinity Study.
The 4% Rule and Its Application
The researchers analyzed historical stock and bond market data over rolling 30-year periods to determine how much a retiree could comfortably withdraw from an investment portfolio without running out of money before they died. The baseline consensus emerged as the 4% Safe Withdrawal Rate (SWR).
If you accumulate a diversified portfolio of equities and fixed-income assets and withdraw exactly 4% of the total value in year one—subsequently adjusting that dollar amount annually to match the rate of inflation—the probability of portfolio survival over a 30-year horizon exceeds 95%.
By inverting the 4% rule, we arrive at the primary engine of financial independence planning: The Rule of 25.
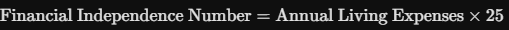
For example, if a comprehensive audit reveals that your household requires exactly $60,000 per year to maintain a comfortable, optimized lifestyle, your target calculation is:
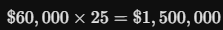
Once your net asset value hits $1.5 million, you have structurally achieved financial independence based on historical market baselines.
Navigating Modern Volatility (The Sequence of Returns Risk)
While the 4% rule is an excellent baseline, modern financial journalists and economists emphasize that a simple 30-year window is insufficient for someone achieving independence early in life (e.g., in their 30s or 40s). If an individual retires right at the start of a massive market crash, they face Sequence of Returns Risk (SRR). Wiping out a significant portion of your portfolio’s principal early on through withdrawals during a bear market severely damages its long-term compounding capacity.
To mitigate this risk, modern financial architects recommend deploying a slightly more conservative 3.25% to 3.5% SWR for early retirement windows spanning 40 to 50 years, or maintaining a dynamic withdrawal strategy that temporarily scales back spending during market downturns.
Part 3: The Three Flavors of Independence
Financial independence is not a binary, one-size-fits-all destination. The personal finance community has developed distinct, specialized frameworks tailored to different lifestyle goals and income topographies.
The FIRE Landscape Comparison
Understanding these distinct variations allows you to align your strategy with your personal values:
| Framework Strategy | Lifestyle Core Philosophy | Portfolio Structure | Target Audience Profile |
| Lean FIRE | Extreme minimalism, radical expenditure compression, and rejection of consumer culture. | Optimized for a low annual budget (typically under $40,000/year). Requires a smaller absolute portfolio. | Individuals who value time over luxury goods; comfortable with off-grid living or high-efficiency urban environments. |
| Fat FIRE | Mainstream abundant lifestyle, preserving high discretionary spending, travel buffers, and premium healthcare reserves. | Built around a large annual budget (typically $100,000+/year). Requires a portfolio exceeding $2.5M. | High-earning corporate executives, business owners, or professionals unwilling to compromise comfort for speed. |
| Coast FIRE | Front-loading retirement savings early in life, then allowing compound interest to do the heavy lifting over time. | Accumulating a core nest egg early that will grow to your target FI number by age 60 without any further contributions. | Professionals who want to downshift immediately to lower-stress, lower-paying passion projects or freelance roles. |
Part 4: Building the Wealth Engine — Maximizing the Gap
To accelerate your timeline to financial independence, you must manipulate the most critical variable in personal wealth building: the Savings Rate. Your savings rate is not determined by how much money you make, but by the size of the gap between your income and your lifestyle expenditures.

An individual earning $250,000 a year who spends $240,000 has a savings rate of just 4%. It will take them more than 50 years to achieve financial independence. Conversely, an individual earning $80,000 who optimizes their expenses to live comfortably on $40,000 boasts a 50% savings rate. They can theoretically achieve complete financial liberation in less than 17 years.
To widen this gap aggressively, you must reject traditional budgeting frameworks that recommend saving whatever is left over at the end of the month. Instead, implement a Reverse Budgeting Protocol. Determine your target savings rate first, automatically route that capital into your investment accounts the moment you are paid, and force your household to dynamically adapt and live entirely on the remaining balance.
Conclusion: The True Currency of Independence
The journey toward financial independence is often exhausting, requiring consistent resistance to societal pressures of conspicuous consumption and keeping up with the lifestyle upgrades of peers. However, the ultimate prize is well worth the discipline.
Money is not merely a tool to buy consumer products; it is liquid security. It is the raw material used to purchase your autonomy. When you achieve financial independence, you stop trading your limited life force for basic survival. You reclaim absolute ownership of your calendar, your mornings, and your creative focus. The true wealth generated by this mathematical journey is the ultimate luxury: the unshakeable freedom to choose exactly how you spend your time on this planet.